What $700,000 buys
This is where the question flips. Below this, buyers ask what they can get. At $700,000 and up, the constraint is usually no longer the house — it is which community you want to be in, and how much of the budget you are willing to spend on that rather than on square footage.
- A well-kept detached home in most established communities, four bedrooms in many, double attached garage in the newer ones.
- A newer or renovated home in the outer southwest and northwest, often with a finished basement and a developed yard.
- Inner-city infill — usually a half-duplex rather than a full detached at this price, but modern and walkable.
What it does not reliably buy is a fully renovated detached home in the premium inner-city southwest communities. That is a different band again.
The question worth asking at this price
Above about $650,000 the buyer pool narrows, and resale becomes a live consideration rather than a theoretical one. Features that are easy to sell at $500,000 — a converted garage, an unusual layout, a heavily personalised renovation — get harder as the price climbs, because the pool of people who want exactly that shrinks.
At this level it is worth asking about every home: who is the next buyer, and is there a large group of them? That question costs nothing now and can be worth tens of thousands later.
Calgary homes currently listed around $700,000
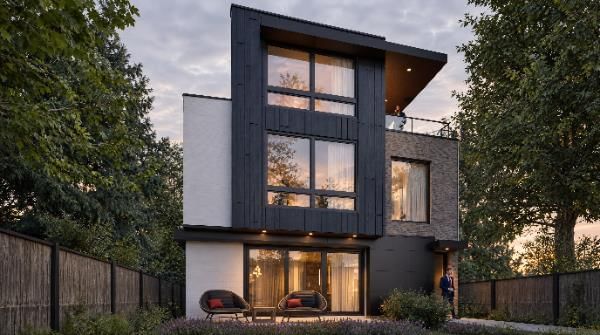 $4,200,0002329 Bowness Road NW
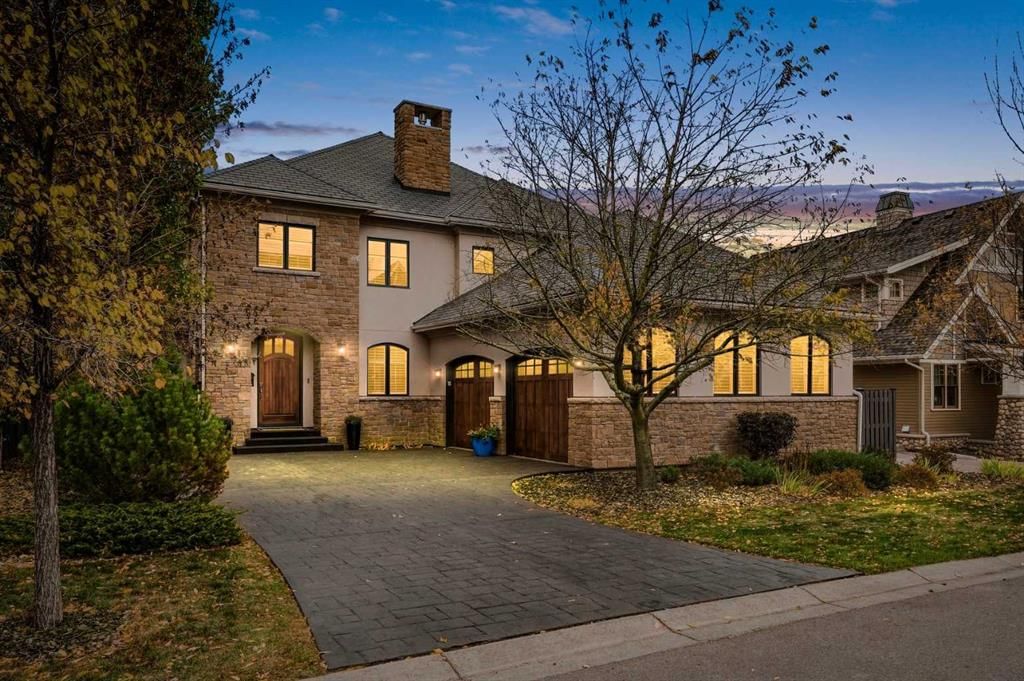 $3,600,00066 Mary Dover Drive SW
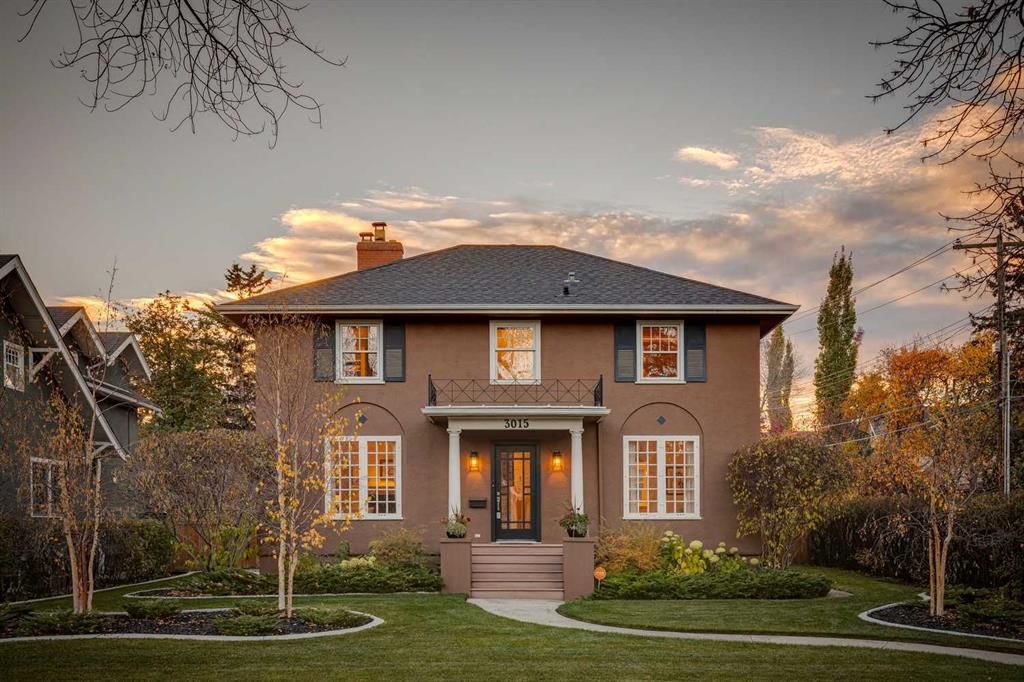 $2,475,0003015 2 Street SW
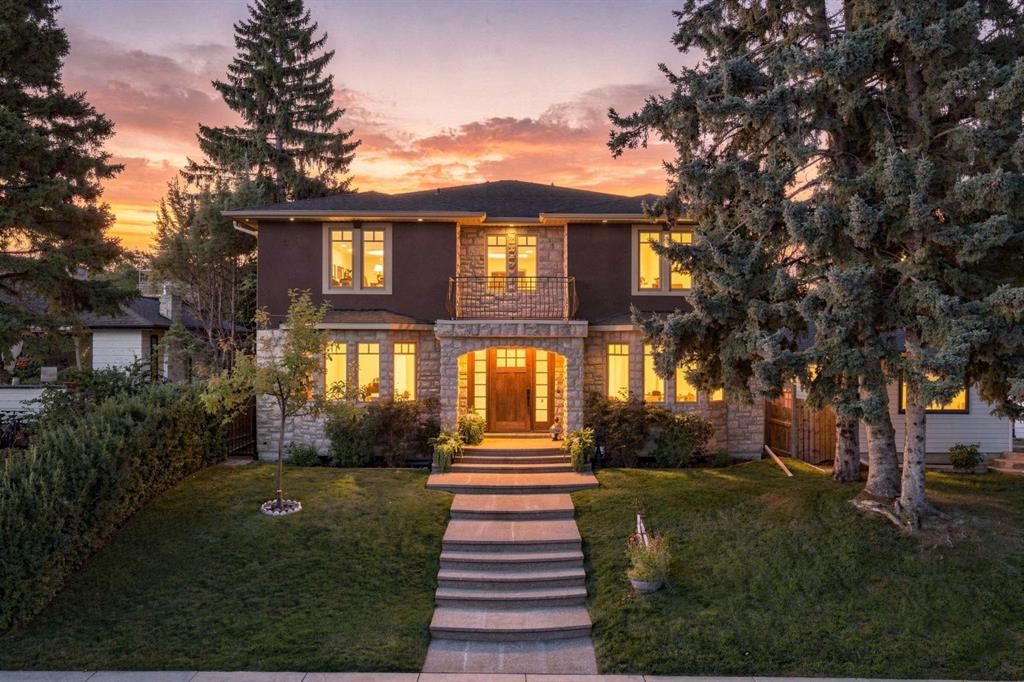 $2,345,000803 25 Avenue NW
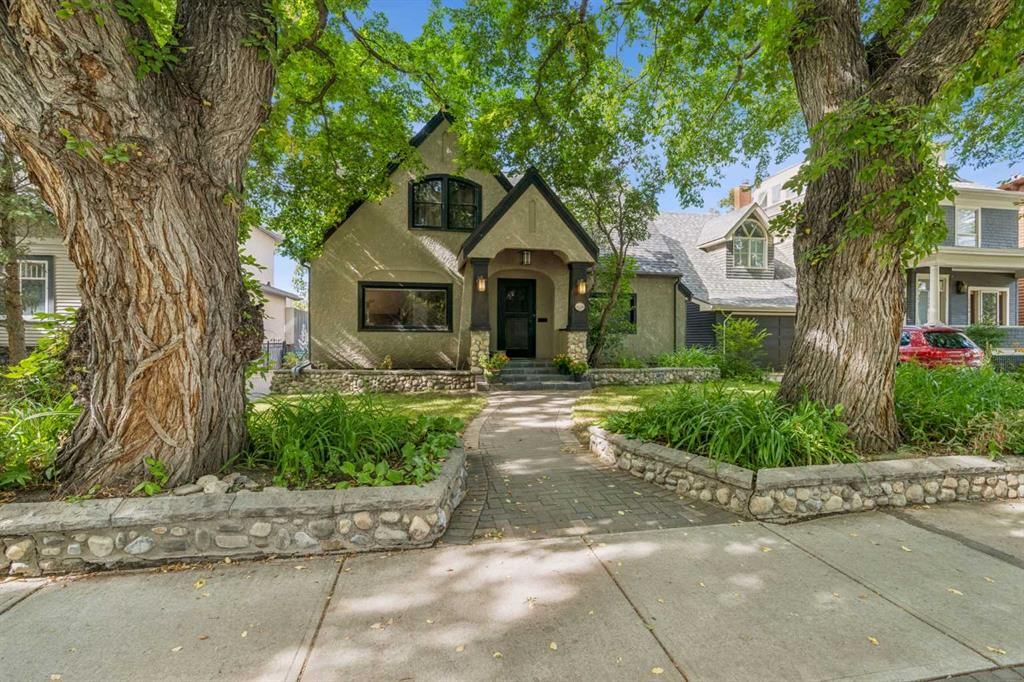 $2,200,000620 Rideau Road SW
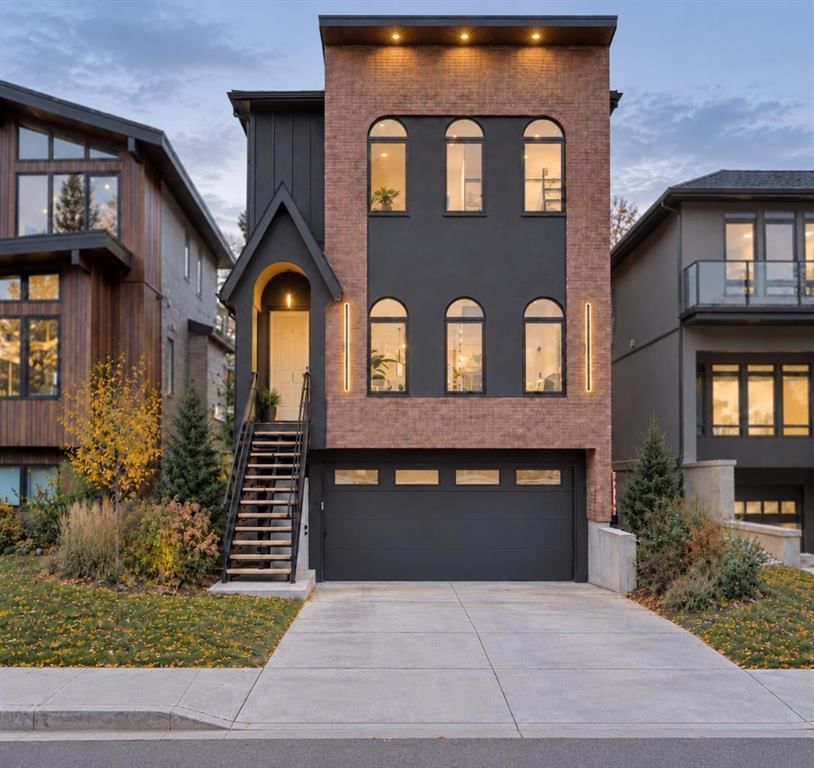 $1,899,0002220 8 Street NE
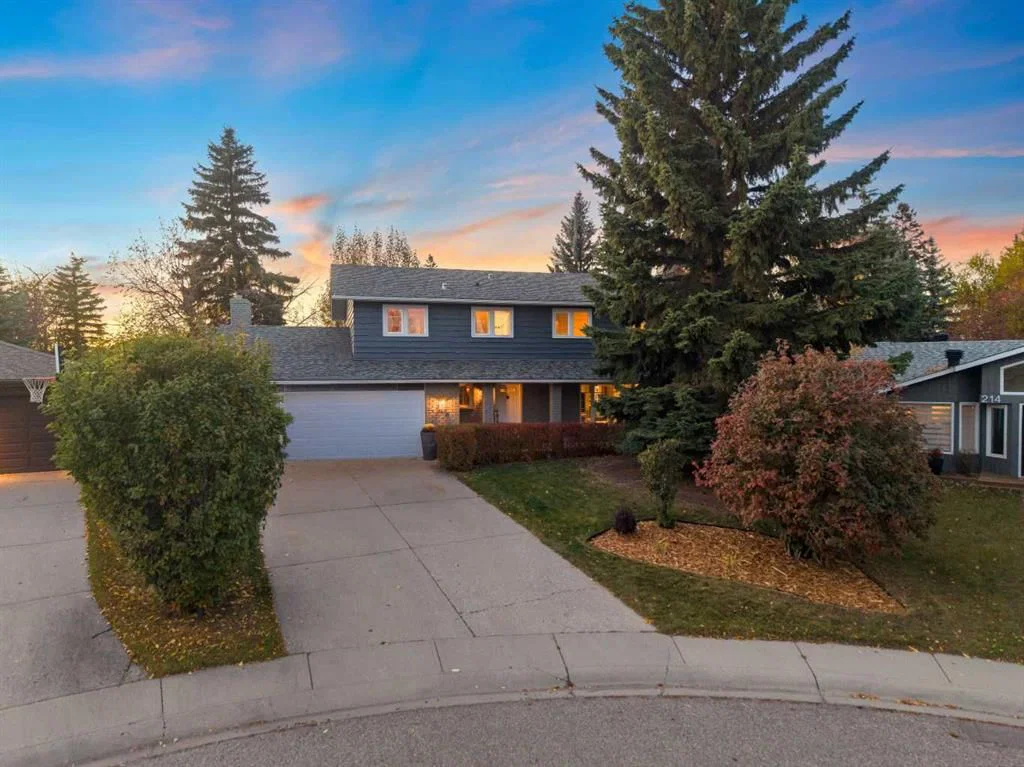 $1,550,000216 Lake Erie Place SE
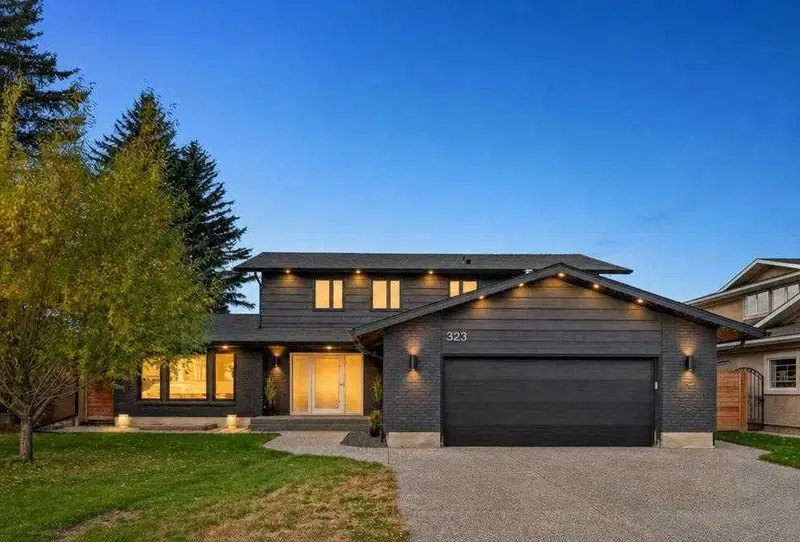 $1,450,000323 Parkview Crescent SE
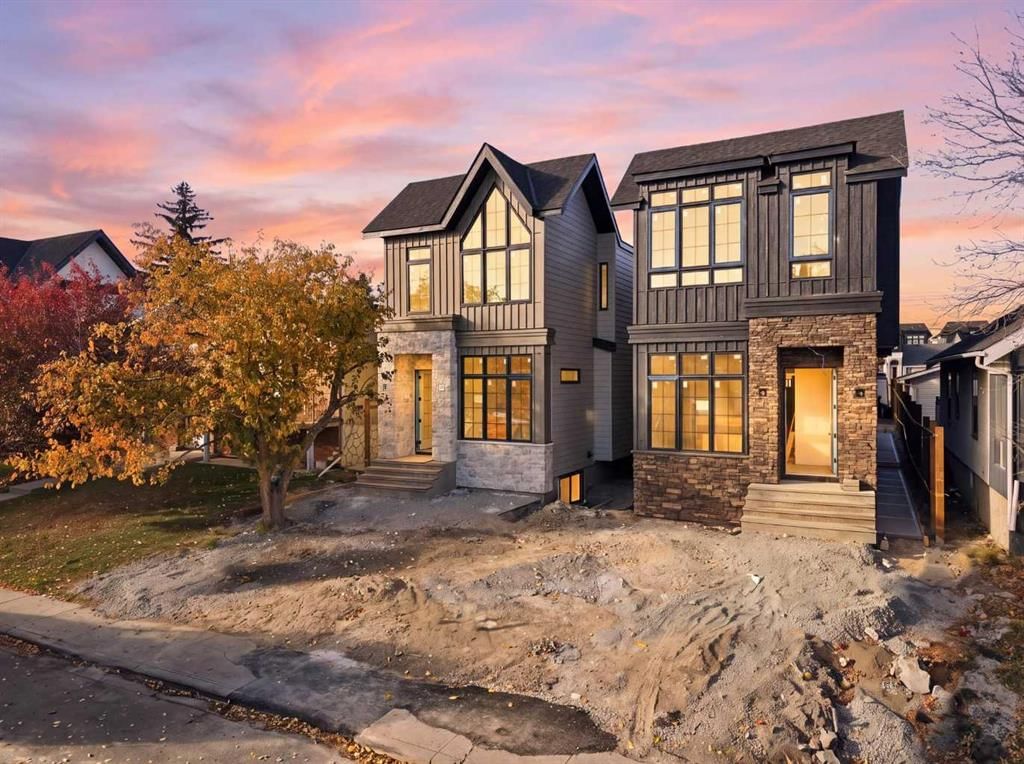 $1,339,800816 21 Avenue NW
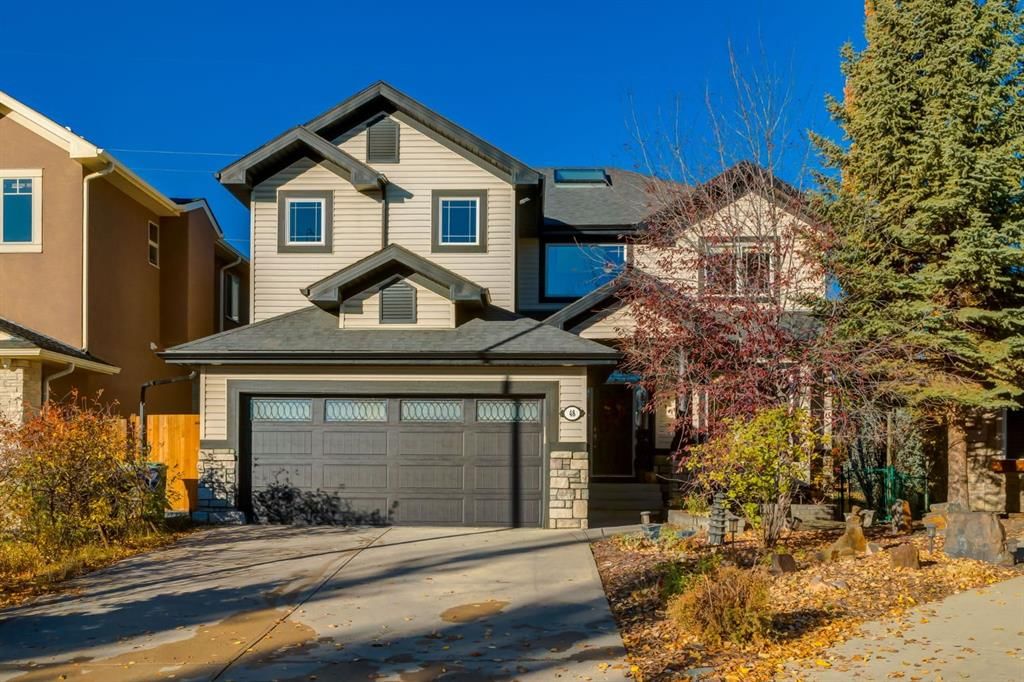 $1,150,00048 Valley Crest Gardens NW
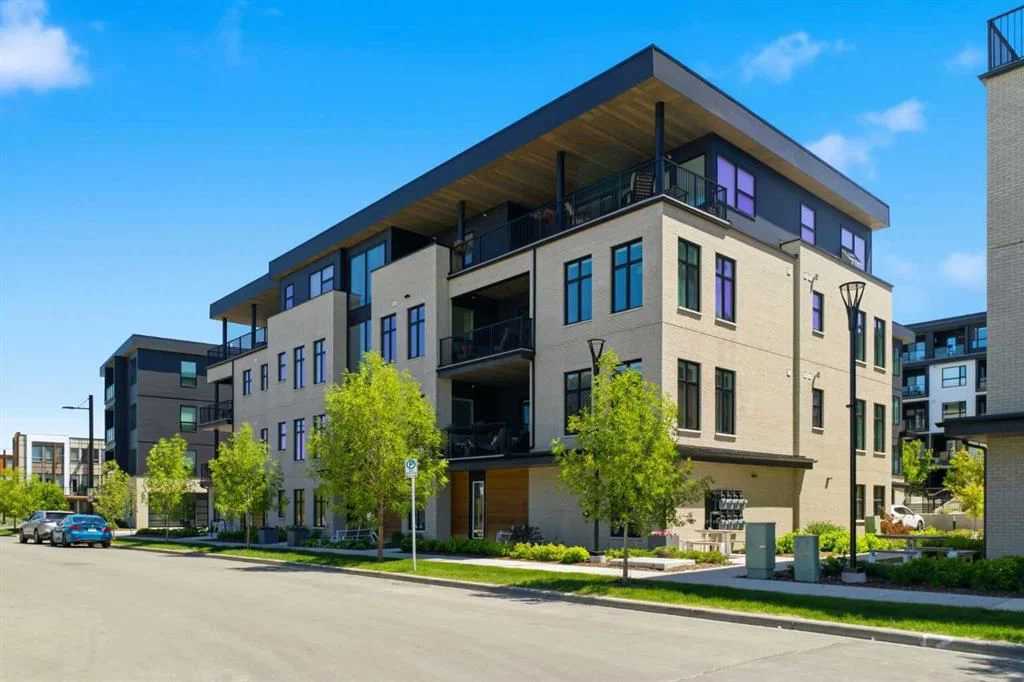 $1,150,000301, 105 Lebel Crescent NW
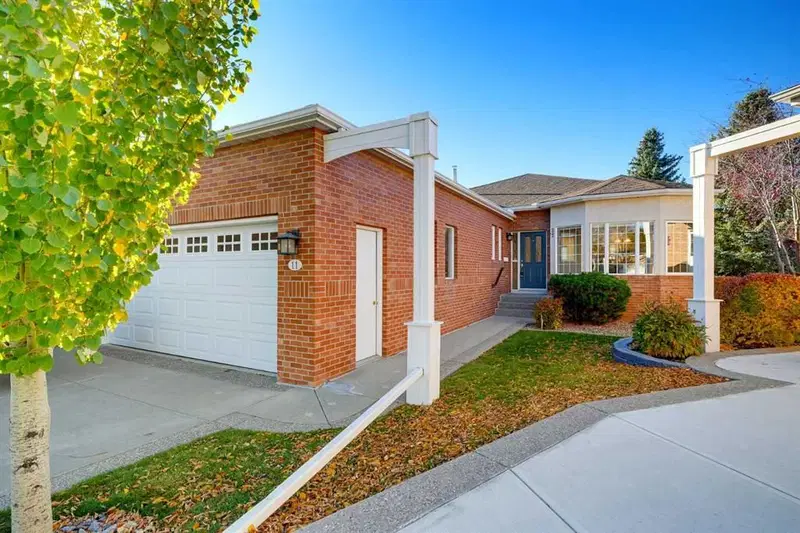 $1,050,00011 Prominence Point SW
Showing 12 of 6101 matching active MLS® listings in Calgary.
More homes for sale in Calgary
- 100 Crestbrook View SW · $1,039,900 · 3 bed · Detached
- 408 49 Avenue SW · $1,024,900 · 2 bed · Detached
- 51 Cougar Ridge Close SW · $989,000 · 3 bed · Detached
- 40 Silver Ridge Court NW · $975,000 · 4 bed · Detached
- 203 St Moritz Drive SW · $949,900 · 3 bed · Detached
- 51 Chapalina Terrace SE · $899,000 · 3 bed · Detached
- 103 St Moritz Terrace SW · $839,900 · 3 bed · Detached
- 2211A 33 Street SW · $839,000 · 3 bed · Semi Detached (Half Duplex)
- 16 Lebel Crescent NW · $824,900 · 2 bed · Row/Townhouse
- 143 Saddlestone Park NE · $799,900 · 5 bed · Detached
- 192 Cornerbrook Road NE · $799,900 · 5 bed · Detached
- 5739 Dalmead Crescent NW · $750,000 · 3 bed · Detached
- 20 Carringham Heights NW · $749,000 · 3 bed · Detached
- 1103 4 Street NE · $724,900 · 3 bed · Row/Townhouse
- 19 Chapman Way SE · $719,000 · 3 bed · Detached
- 808 Avonlea Place SE · $714,000 · 3 bed · Detached
- 47 Chaparral Common SE · $700,000 · 3 bed · Detached
- 48 Deermont Way SE · $674,900 · 3 bed · Detached
- 101 Langton Drive SW · $660,000 · 3 bed · Detached
- 507 Hidden Vale Place NW · $650,000 · 3 bed · Detached
- 108 Elgin Manor SE · $650,000 · 2 bed · Detached
- 216 Lucas Place NW · $649,000 · 2 bed · Detached
- 116 Rockyledge Crescent NW · $648,000 · 2 bed · Detached
- 250 Aquila Way NW · $645,000 · 3 bed · Detached
- 38 Somerside Crescent SW · $624,900 · 3 bed · Detached
- 4316 53 Street NE · $600,000 · 3 bed · Detached
- 436 Huntley Way NE · $599,999 · 2 bed · Detached
- 248 Douglas Ridge Green SE · $599,900 · 4 bed · Detached
- 115 Skyview Springs Gardens NE · $589,000 · 3 bed · Detached
- 4724 Nipawin Crescent NW · $574,900 · 3 bed · Detached
- 60 Walcrest Gate SE · $535,000 · 3 bed · Semi Detached (Half Duplex)
- 189 Carringvue Way NW · $529,900 · 3 bed · Semi Detached (Half Duplex)
- 6839 Huntridge Hill NE · $529,900 · 3 bed · Detached
- 307, 39 Quarry Gate SE · $529,000 · 2 bed · Apartment
- 107 Coach Side Terrace SW · $525,000 · 2 bed · Row/Townhouse
- 3, 1930 26A Street SW · $525,000 · 2 bed · Row/Townhouse
- 75 Cedarwood Lane SW · $480,000 · 3 bed · Semi Detached (Half Duplex)
- 127 Erin Meadow Crescent SE · $479,900 · 3 bed · Detached
- 237 Mt Aberdeen Circle SE · $475,000 · 3 bed · Detached
- 246 Cranbrook Square SE · $449,900 · 2 bed · Row/Townhouse
- 76 Sierra Morena Green SW · $419,900 · 2 bed · Row/Townhouse
- 83 Savanna Park NE · $415,000 · 3 bed · Row/Townhouse
- 101, 60 Sage Hill Walk NW · $415,000 · 2 bed · Apartment
- 606 34 Avenue NE · $409,900 · 3 bed · Semi Detached (Half Duplex)
- 130 MacEwan Park Way NW · $400,000 · 3 bed · Semi Detached (Half Duplex)
- 1206, 1500 7 Street SW · $399,900 · 2 bed · Apartment
- 6624 Huntsbay Road NW · $394,000 · 3 bed · Row/Townhouse
- 1410, 11 Mahogany Row SE · $359,900 · 2 bed · Apartment
- 427 Redstone View NE · $349,990 · 4 bed · Row/Townhouse
- 316, 30 Cranfield Link SE · $345,000 · 2 bed · Apartment
- 6403, 20295 Seton Way SE · $330,000 · 2 bed · Apartment
- 6207 Beaver Dam Way NE · $325,000 · 1 bed · Semi Detached (Half Duplex)
- 311 Killarney Glen Court SW · $325,000 · 3 bed · Row/Townhouse
- 143 Rundleson Way NE · $319,900 · 3 bed · Semi Detached (Half Duplex)
- 41, 116 Silver Crest Drive NW · $315,000 · 2 bed · Row/Townhouse
- 18 Auburn Bay Common SE · $310,000 · 2 bed · Row/Townhouse
- 3209, 99 Copperstone Park SE · $299,900 · 2 bed · Apartment
- 1004, 1121 6 Avenue SW · $255,000 · 1 bed · Apartment
- 402C, 5601 Dalton Drive NW · $190,000 · 2 bed · Apartment
- 2110, 221 6 Avenue SE · $179,900 · 1 bed · Apartment
What income do you need for a $700,000 home?
Rather than a required-income figure — which cannot be right for more than a handful of readers — here is what a lender is actually adding up when they answer this for you.
Two ratios do the work. On an insured mortgage, CMHC allows a gross debt service ratio of 39%: mortgage payment, property tax, heating and half of any condo fee, measured against your gross income. Then a total debt service ratio of 44%, which adds everything else you owe. Both must pass.
What goes into the housing half is the part buyers underestimate. Property tax on the specific home, not an average. Heating a large two-storey house rather than an apartment. Half the condo fee where there is one. Two homes listed at $700,000 can therefore qualify you for different mortgages, and the more expensive one to run is the one that costs you buying power.
The rest of the sequence: the minimum down payment here is $45,000 — 5% of the first $500,000 plus 10% of the next $200,000 — and you are qualified at the greater of your contract rate plus two percentage points, or 5.25%, rather than at the rate you will pay.
See what counts against what you can borrow for the full list, and talk to a Calgary mortgage broker before you assume a price range.