The fork at $800,000
This price splits cleanly into two very different purchases, and buyers who do not choose deliberately tend to drift for months.
- A large, newer home in an outer community — often close to 2,500 square feet above grade, four or five bedrooms, triple garage in some, finished basement, newer everything. Commute is the cost.
- A good detached home in an established inner-ring community — smaller, older, mature trees, walkable, close to the core. You are paying for the land and the location.
Both are sound. They are not comparable on square footage, and comparing them that way is what makes this band frustrating.
What to scrutinise at this level
Renovation quality starts mattering more than renovation quantity. At $800,000 a lot of homes have been updated, and the question becomes whether the work was permitted, done properly, and to a standard the next buyer will accept. Ask for permits on any structural, electrical or plumbing work. An unpermitted basement development is a discount, not a feature.
See also: the five questions that test whether an agent knows the area →
Calgary homes currently listed around $800,000
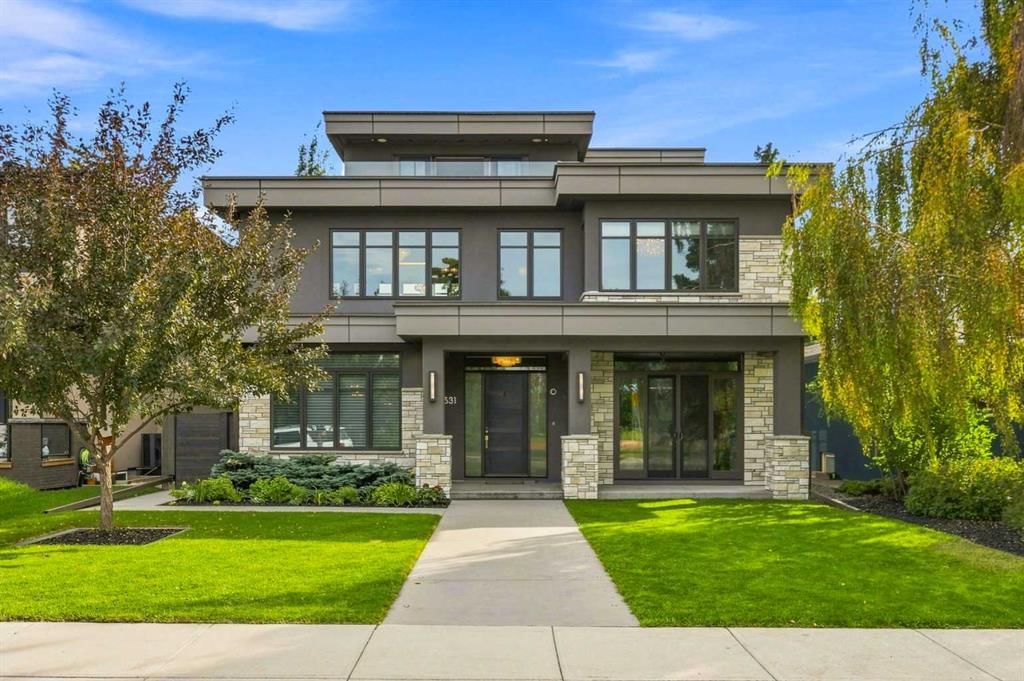 $4,088,000531 47 Avenue SW
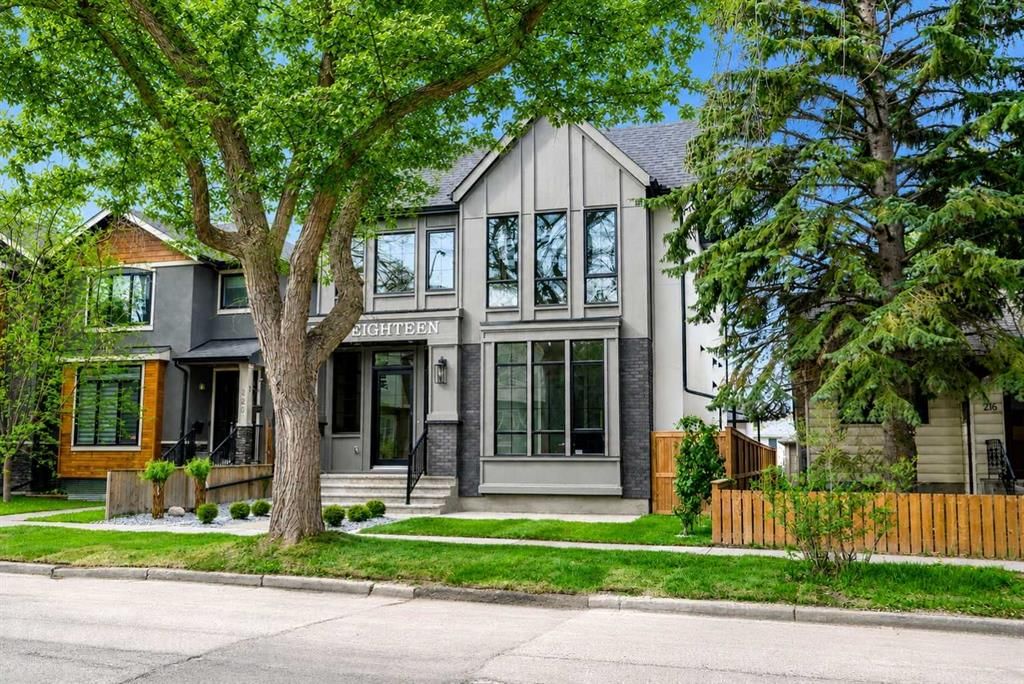 $1,995,000218 19 Avenue
 $1,650,0004110 16A Street SW
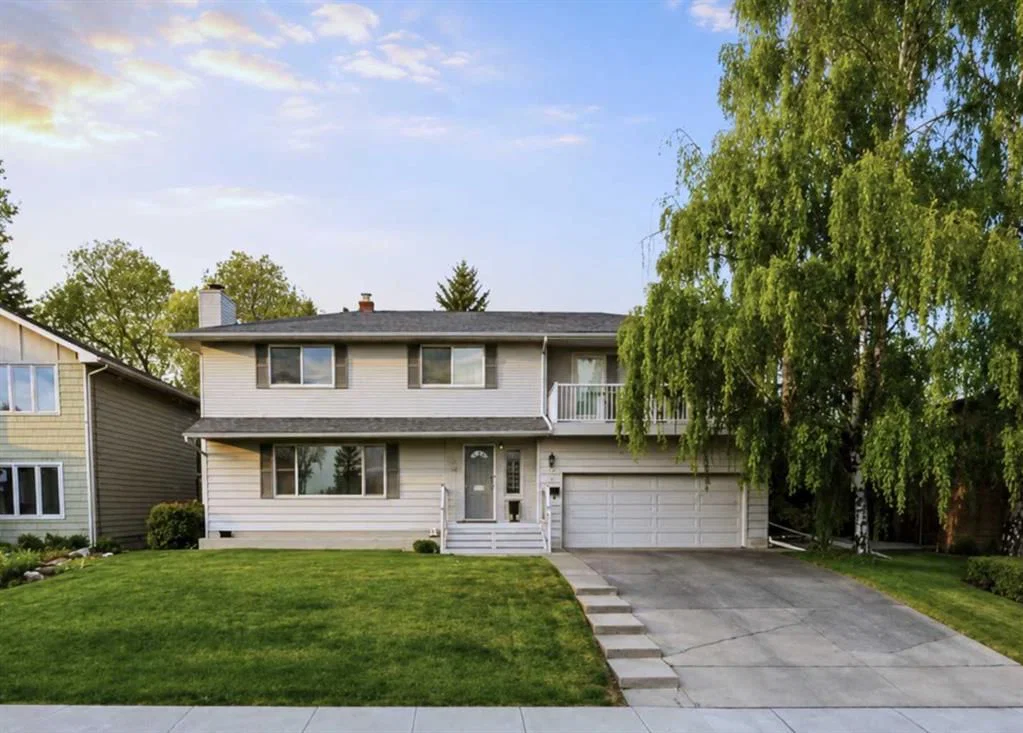 $1,650,0004015 14A Street SW
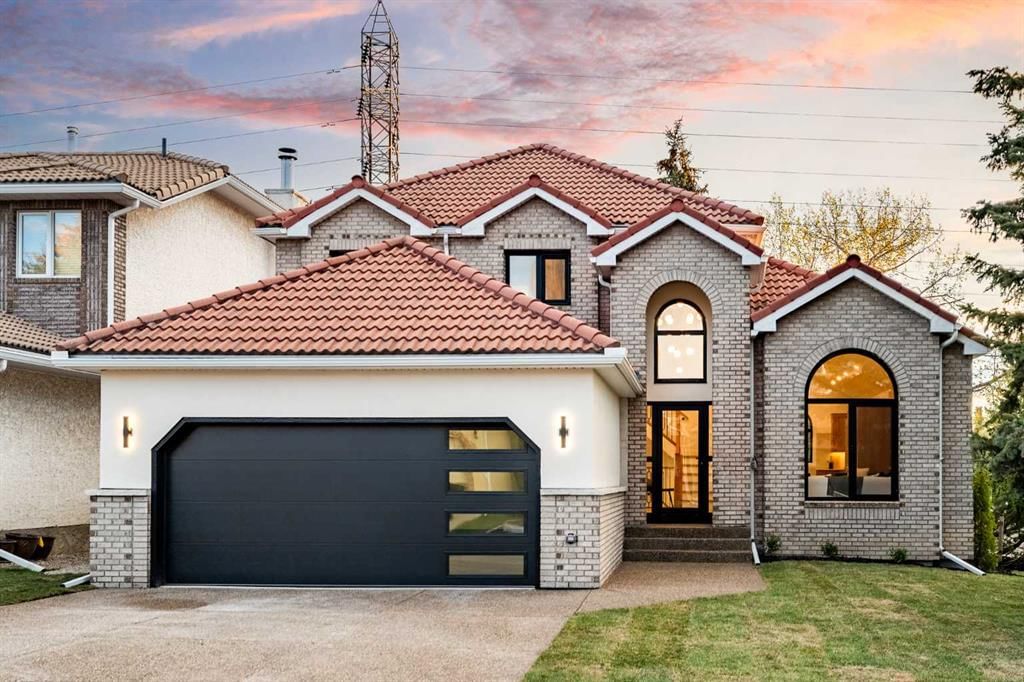 $1,575,0003 Varsity Ridge Terrace NW
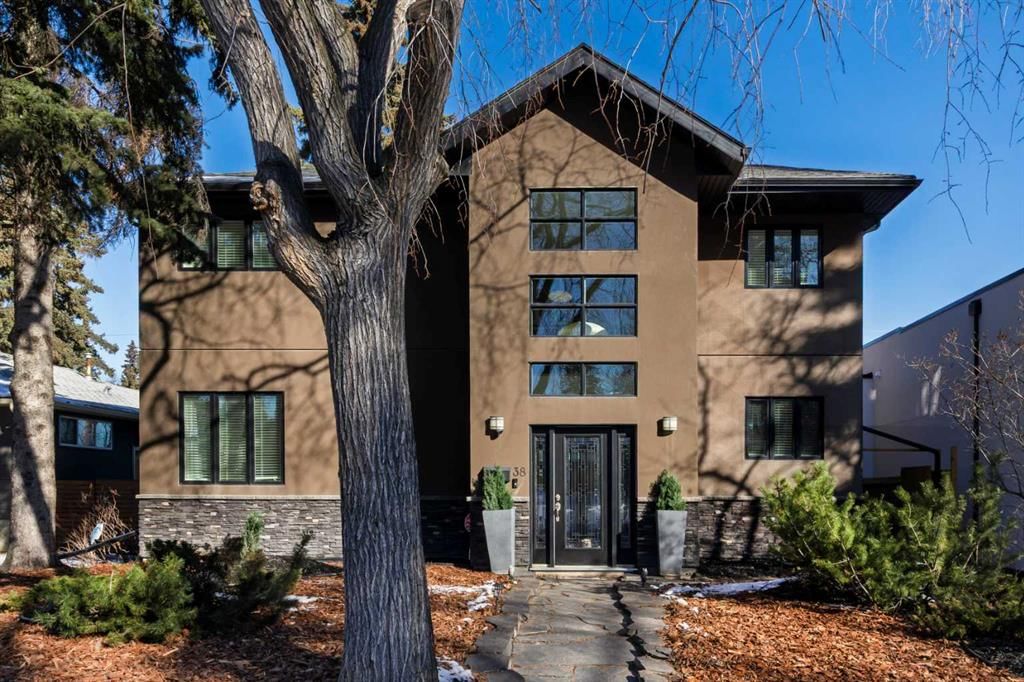 $1,524,90038 Lissington Drive SW
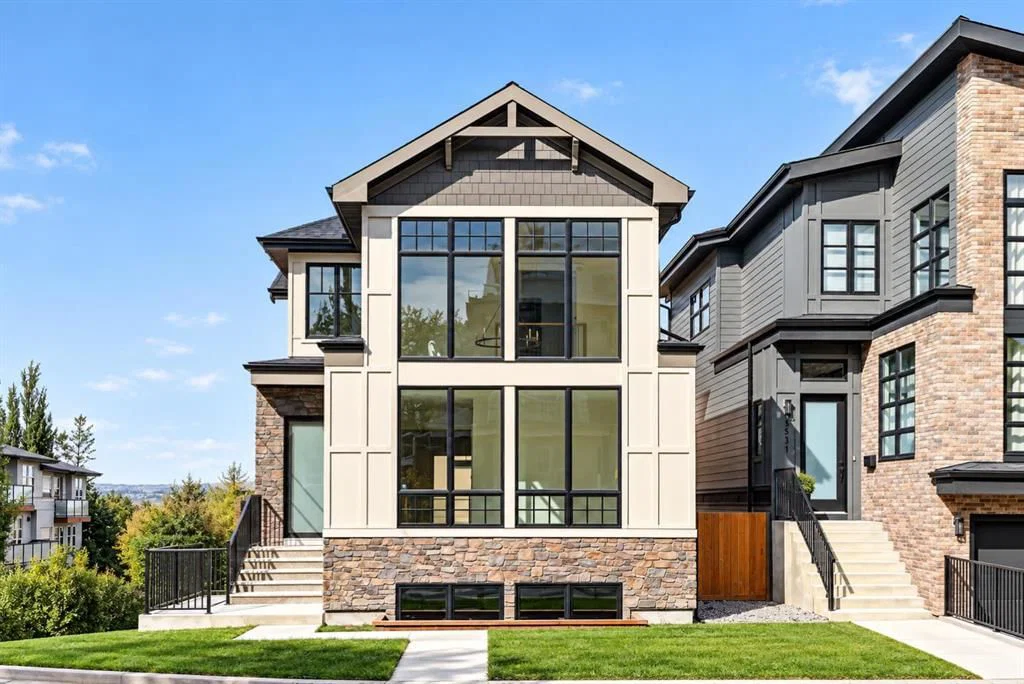 $1,439,0001516 22 Avenue SW
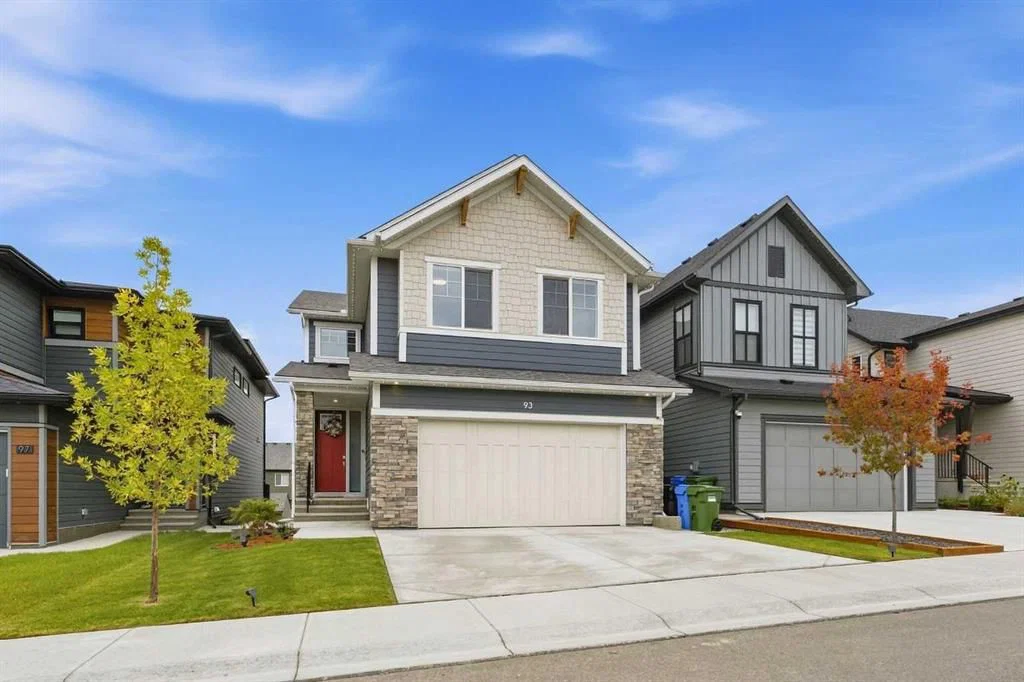 $1,299,00093 Rochester Way NW
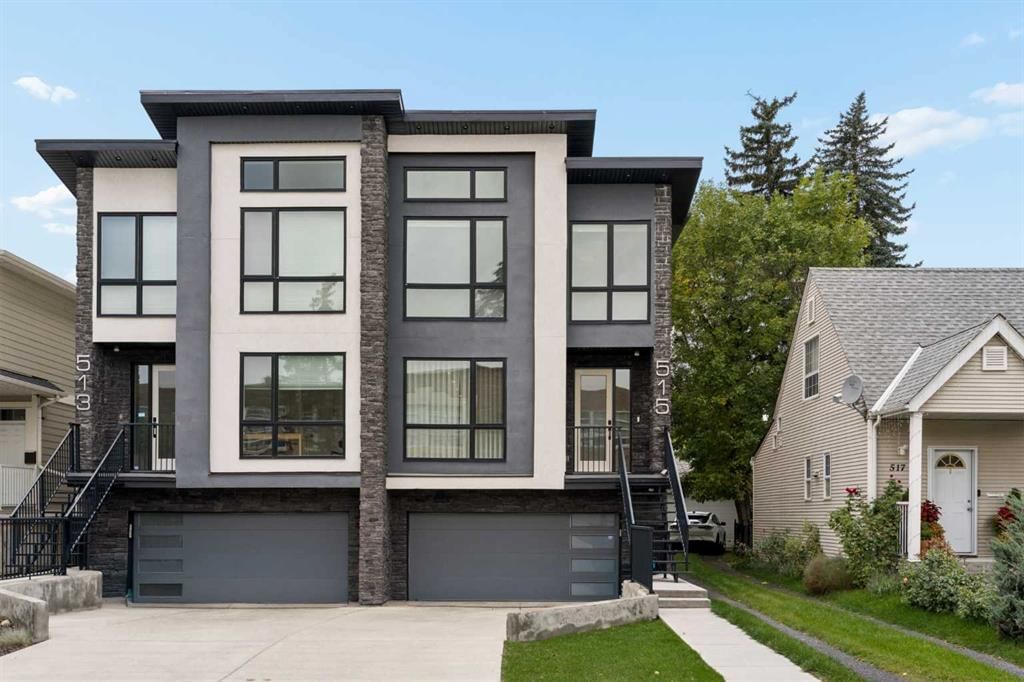 $1,199,900515 18 Street NW
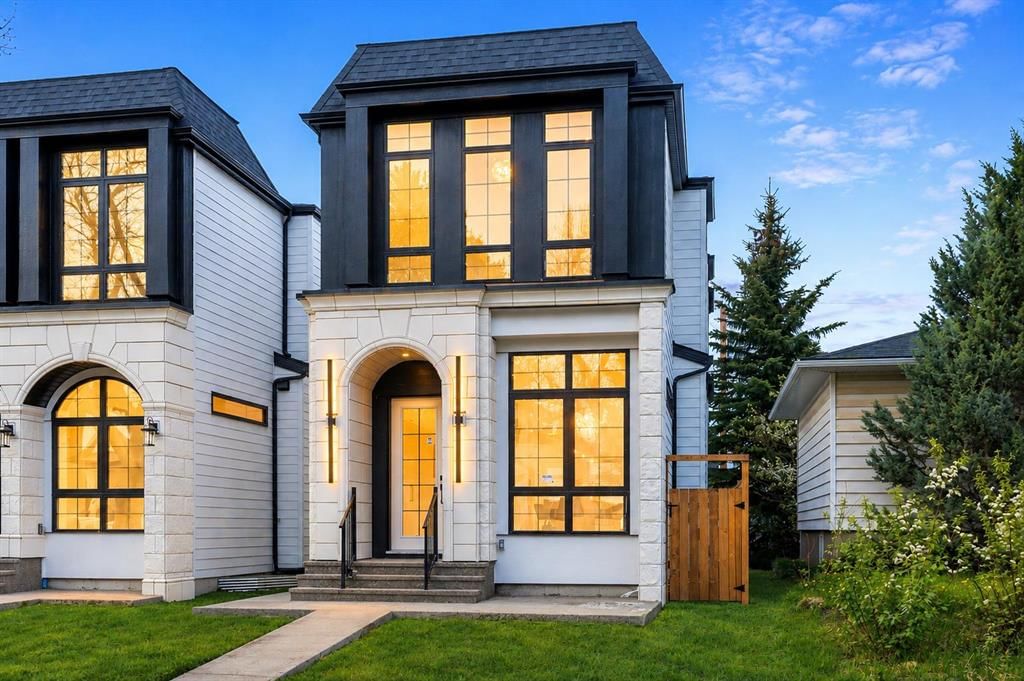 $1,174,900510 29 Avenue NW
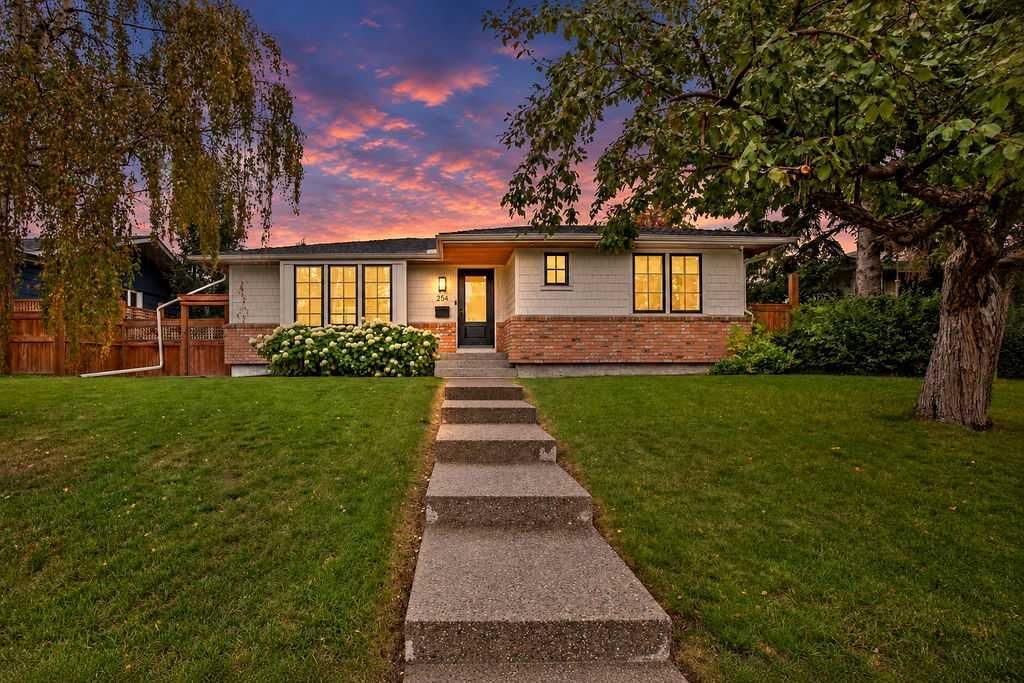 $1,099,000256 Westminster Drive SW
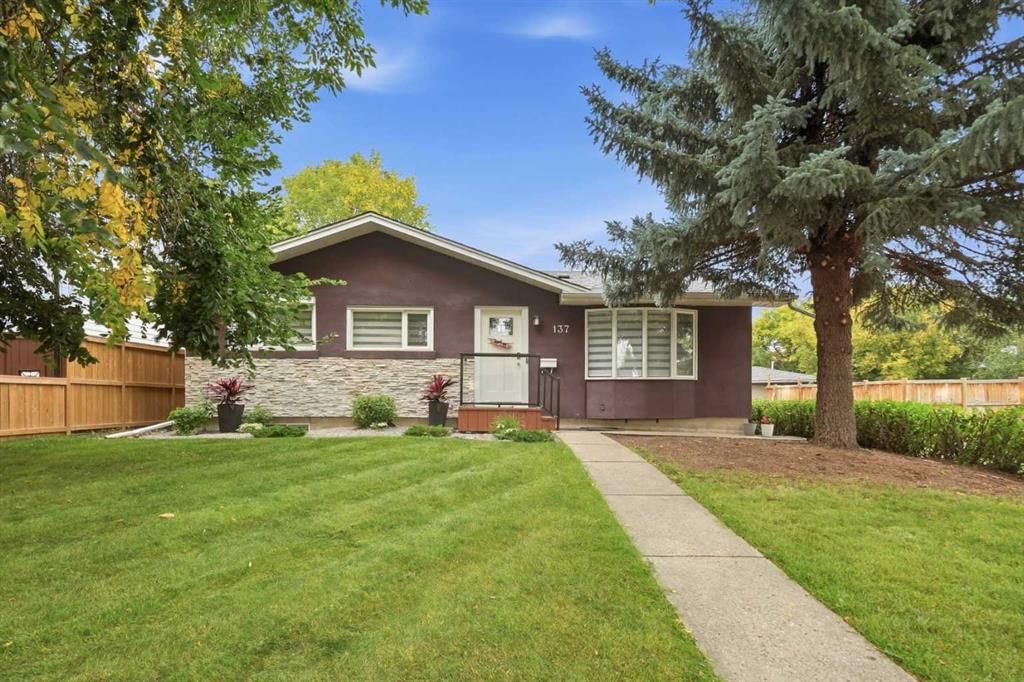 $1,074,500137 Lissington Drive SW
Showing 12 of 6259 matching active MLS® listings in Calgary. Prices and availability update every 10 minutes.
More homes for sale in Calgary
- 4102, 1188 3 Street SE · $1,050,000 · 2 bed · Apartment
- 66 Royal Oak Grove NW · $969,000 · 3 bed · Detached
- 70 Auburn Springs Park SE · $959,900 · 3 bed · Detached
- 23 Brown Crescent NW · $860,000 · 3 bed · Detached
- 4629 72 Street NW · $839,900 · 3 bed · Detached
- 112 Cityside Park NE · $799,000 · 2 bed · Detached
- 595 Everbrook Way SW · $784,900 · 3 bed · Detached
- 23 Cranberry Circle SE · $779,900 · 3 bed · Detached
- 72 Creekview Common SW · $765,000 · 3 bed · Detached
- 313 Walgrove Terrace SE · $760,000 · 3 bed · Detached
- 1916 Green Ridge Road SW · $759,900 · 3 bed · Detached
- 180 Howse Crescent NE · $749,888 · 4 bed · Detached
- 327 Panamount Point NW · $745,000 · 3 bed · Detached
- 6316 Crowchild Trail SW · $739,900 · 3 bed · Detached
- 15 Wellington Place SW · $724,900 · 1 bed · Detached
- 62 Panamount Plaza NW · $719,900 · 3 bed · Detached
- 1506 36 Street SE · $695,000 · 3 bed · Detached
- 2015 Palliser Drive SW · $695,000 · 4 bed · Detached
- 1823 18A Street SW · $639,900 · 4 bed · Detached
- 1, 523 34 Street NW · $618,816 · 3 bed · Row/Townhouse
- 265 Everglen Rise SW · $605,000 · 3 bed · Detached
- 96 Buffaloberry Manor SE · $589,900 · 4 bed · Detached
- 31 Red Embers Lane NE · $575,000 · 4 bed · Detached
- 303 Saddlebrook Circle NE · $569,950 · 3 bed · Detached
- 723 Canfield Place SW · $565,000 · 2 bed · Detached
- 3, 315 3 Street NE · $550,000 · 3 bed · Row/Townhouse
- 2016 46 Street SE · $550,000 · 3 bed · Detached
- 7944 Huntington Road NE · $539,900 · 2 bed · Detached
- 7711 39 Avenue NW · $529,900 · 3 bed · Detached
- 13 Saddlecrest Green NE · $529,900 · 3 bed · Detached
- 4819 Memorial Drive SE · $510,000 · 3 bed · Detached
- 280 Rockyspring Grove NW · $489,900 · 3 bed · Row/Townhouse
- 36 Hamptons Link NW · $488,000 · 3 bed · Row/Townhouse
- 28 Martinglen Way NE · $474,900 · 3 bed · Semi Detached (Half Duplex)
- 34 Royal Manor NW · $462,888 · 3 bed · Row/Townhouse
- 155 Sandarac Way NW · $449,900 · 2 bed · Semi Detached (Half Duplex)
- 404, 428 Nolan Hill Drive NW · $449,900 · 2 bed · Row/Townhouse
- 156 Walden Lane SE · $445,000 · 3 bed · Row/Townhouse
- 63 Rundleson Way NE · $429,900 · 3 bed · Detached
- 306, 3501 15 Street SW · $424,888 · 2 bed · Apartment
- 80, 23 Glamis Drive SW · $420,000 · 3 bed · Row/Townhouse
- 111 Midbend Place SE · $419,900 · 3 bed · Row/Townhouse
- 2412, 265 Wolf Willow Boulevard SE · $400,000 · 2 bed · Apartment
- 505, 108 Waterfront Court SW · $399,900 · 2 bed · Apartment
- 65, 70 Beacham Way NW · $399,900 · 2 bed · Semi Detached (Half Duplex)
- 280 Copperstone Cove SE · $379,900 · 2 bed · Row/Townhouse
- 205, 39 Quarry Gate SE · $355,000 · 1 bed · Apartment
- 42, 380 Bermuda Drive NW · $349,900 · 3 bed · Row/Townhouse
- 1204, 47 Creekview Gardens SW · $345,900 · 2 bed · Apartment
- 204, 111 Tarawood Lane NE · $309,000 · 2 bed · Row/Townhouse
- 1305, 47 Creekview Gardens · $306,495 · 2 bed · Apartment
- 302, 20 Sage Hill Terrace NW · $300,000 · 2 bed · Apartment
- 1304, 81 Legacy Boulevard SE · $277,500 · 2 bed · Apartment
- 1806, 3820 Brentwood Road NW · $260,000 · 1 bed · Apartment
- 302, 1323 15 Avenue SW · $239,000 · 2 bed · Apartment
- 420, 7180 80 Avenue NE · $215,000 · 1 bed · Apartment
- 301, 1904 10 Street SW · $200,000 · 1 bed · Apartment
- 506, 340 14 Avenue SW · $157,000 · 1 bed · Apartment
- 110, 335 Garry Crescent NE · $149,900 · 1 bed · Apartment
- 826, 110 18A Street NW · $1,690 · Other
What income do you need for an $800,000 home?
We will not publish a figure — but at this price there is a real decision behind the question, which is whether you are buying with an insured or an uninsured mortgage. It changes the arithmetic more than a few thousand dollars of income does.
The minimum down payment at $800,000 is $55,000: 5% of the first $500,000 plus 10% of the next $300,000. Insured mortgages remain available up to a $1,500,000 purchase price, so this band still has the choice. Twenty per cent — $160,000 — removes the default insurance premium and moves you into uninsured lending.
Neither is automatically better. Insured mortgages often carry slightly lower interest rates, and the premium is normally added to the mortgage rather than paid in cash; in Alberta there is no provincial sales tax on that premium, unlike Ontario, Quebec and Saskatchewan. Against that, 20% down means a smaller loan and no premium at all. Insured lending also brings fixed rules — debt service ratios of 39% and 44%, and a minimum credit score of 600 for at least one borrower — where uninsured lenders set their own limits.
Either way you are qualified at the greater of your contract rate plus two percentage points, or 5.25%. Should you put 5%, 10% or 20% down works through the trade-off, and our affordability page covers what reduces the number.